
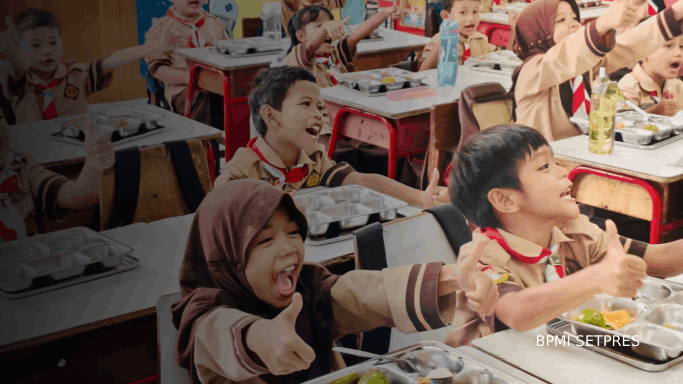
The implementation of the free nutritious meals (makan bergizi gratis/MBG) program, which involves numerous foundations as government partners, requires more than readiness to provide meals to beneficiaries. The program also involves administrative and tax matters that require serious attention, as the use of government funds to implement a social program remains subject to prevailing tax regulations.
This was reiterated by Tax Counselor at the Ciawi Primary Tax Office Adam Siaga Utama during a tax class held by the office on Friday (7/8/2026). He explained that a foundation’s involvement in implementing the MBG program does not automatically exempt it from tax obligations.
“Once again, the implementation of the free nutritious meals program remains subject to tax obligations,” Adam said in a statement, as quoted from the official website of the Directorate General of Taxes (DGT).
“The output of the MBG program is not limited to fulfilling the nutritional needs of beneficiaries, but also includes fulfilling the state’s right to tax revenue,” he added.
The MBG program is one of the government’s initiatives to improve nutritional fulfillment among the public and has been designated as a National Strategic Project. Under the program, foundations play an important role, including providing facilities for Nutrition Fulfillment Service Units and ensuring that meals reach beneficiary groups. In this capacity, foundations serve as government assistance recipients and are also classified as corporate taxpayers.
Adam also reminded that a foundation’s nonprofit or social nature does not automatically eliminate its tax obligations. Funds received from the government for the implementation of the MBG program may still have tax implications because there is a relationship between the party providing the funds and the party receiving and carrying out the activities. Government assistance provided by the National Nutrition Agency to foundations is subject to Article 23 Income Tax withholding obligations in accordance with applicable regulations.
Therefore, foundation administrators need to ensure that all tax administration requirements are properly fulfilled. Foundations must have a Taxpayer Identification Number (NPWP), maintain proper books of account, and retain transaction documents and records for the required period. Tax obligations may also arise from various expenditures incurred during the program, including honorarium payments, vehicle or building rentals, construction services, and payments for the provision of facilities. Each type of transaction may be subject to different tax treatment and obligations.
Such compliance should not be viewed merely as an administrative requirement. Proper bookkeeping and record-keeping can help foundations clearly track their receipts and expenditures while determining the tax obligations they need to fulfill. From a governance perspective, well-maintained administration is also essential to ensuring that the use of public funds can be accounted for transparently.
According to Adam, the success of the MBG program should not be measured solely by whether nutritious meals are delivered to the public. Program implementation should also go hand in hand with fulfilling obligations to the state through tax compliance.
Foundations involved in the MBG program need to have an adequate understanding of applicable tax regulations. Compliance from the outset can help prevent administrative issues in the future while strengthening program governance. In this way, the benefits of MBG will not only be felt by beneficiaries receiving nutritious meals, but will also be reflected in the orderly, transparent, and accountable management of public funds.
Also Read:
Complete List of Tax Account Codes and Tax Payment Type Codes for e-Billing
DGT Regulation Number 11 of 2025
Breaking Down the Article 21 Withholding Tax Provisions
