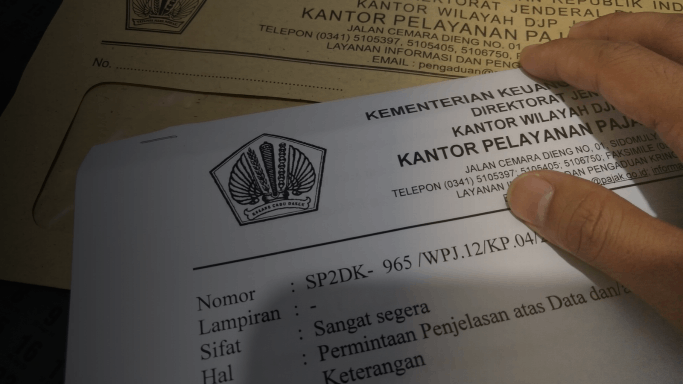
The Core Tax Administration System, known as Coretax, has transformed the Directorate General of Taxes’ (DGT) oversight approach from partial manual reviews to integrated, data-driven monitoring. One of the instruments used by the DGT to assess taxpayers’ substantive compliance is the request for explanation of data and/or information (surat permintaan penjelasan atas data dan/atau keterangan/SP2DK).
SP2DKs essentially serve as a means of clarification and taxpayer guidance. Through this mechanism, taxpayers can explain questioned data and correct errors in fulfilling their tax obligations before a matter proceeds to the enforcement stage. In practice, however, resolving an SP2DK can present challenges when taxpayers need to amend their tax returns to pay outstanding taxes.
These challenges arise when data in SP2DKs generated by Coretax are presented in aggregate or consolidated form. System findings based on specific exposure codes do not always align with tax return formats, which require detailed reporting at the transaction level. This discrepancy makes it difficult for taxpayers to trace the source of discrepancies and determine the appropriate amendments.
Oversight Framework
Taxpayer compliance oversight is governed by Minister of Finance Regulation No. 111 of 2025 (PMK 111/2025), with technical guidance provided in Circular Letter of the Director General of Taxes No. SE-8/PJ/2026 (SE-8/PJ/2026). Effective July 15, 2026, SE-8/PJ/2026 revoked and replaced several previous provisions, including SE-05/PJ/2022, to align oversight processes with the Coretax system.
The DGT divides compliance oversight into three categories. First, oversight of registered taxpayers through requests for explanation of data and/or information (P2DK), advisory letters, and warning letters. Second, oversight of unregistered taxpayers through extensification activities to assess whether they meet the subjective and objective requirements for tax registration. Third, regional oversight through data collection activities (kegiatan pengumpulan data/KPD), which include regional-based KPD, analytical KPD, and KPD activities outside regular duties and functions.
Oversight of registered taxpayers is conducted through substantive compliance reviews (penelitian kepatuhan material/PKM), which aim to assess the fulfillment of tax obligations. SE-8/PJ/2026 classifies these reviews into three types based on their scope and depth of analysis.
Comprehensive reviews cover all tax types and involve analysis of business processes, financial statements, and transfer pricing for tax years preceding the current year. Limited reviews cover one or several tax types and involve a narrower scope of analysis. Meanwhile, automated reviews are conducted by Coretax using specific data and can accelerate the issuance of SP2DKs to as little as one business day.
Oversight planning is centrally coordinated by the Taxpayer Compliance Committee, which is authorized to establish an annual list of priority taxpayers for oversight (daftar prioritas pengawasan/DPP).
SP2DK and BAP2DK Mechanisms
When a substantive compliance review identifies anomalies or indications of noncompliance, the head of a tax service office (kantor pelayanan pajak/KPP), through an account representative (AR), may issue an SP2DK. The letter can be delivered through the taxpayer’s Coretax account, email, facsimile, postal service, or in person.
Taxpayers must submit their responses within 14 calendar days. This period may be extended by a maximum of seven calendar days, provided that taxpayers submit written notification before the initial deadline expires.
The clarification process and data review conducted between taxpayers and the DGT are documented in the minutes of the request for explanation of data and/or information (berita acara pelaksanaan permintaan penjelasan atas data dan/atau keterangan/BAP2DK), previously known as the minutes of request for information (berita acara permintaan keterangan/BAPK).
The BAP2DK records conclusions regarding data validity and recommendations for follow-up action. Possible outcomes include case closure without adjustments, recommendations to amend tax returns, or proposals for a tax audit or a preliminary evidence examination if indications of a criminal offense are found.
If the clarification process leads to a recommendation to amend a tax return, taxpayers must follow up on the findings through the amendment mechanism prescribed under tax regulations. This becomes problematic when the data in an SP2DK do not provide sufficient transaction-level detail to identify and calculate the tax shortfall accurately.
Taxpayers’ Right to Amend Tax Returns
The legal basis for amending tax returns is Law No. 6 of 1983 on General Provisions and Tax Procedures, as amended several times, most recently by Law No. 6 of 2023 on the Enactment of Government Regulation in Lieu of Law No. 2 of 2022 on Job Creation into Law (the General Tax Provisions Law, or UU KUP).
Article 8 paragraph (1) of the UU KUP grants taxpayers the right to voluntarily amend previously submitted tax returns through a written statement, provided that the DGT has not yet commenced an audit. This provision forms part of the self-assessment system, under which taxpayers are responsible for calculating, paying, and reporting their taxes.
Amending a tax return to increase the amount of tax payable may result in administrative interest penalties. These provisions are stipulated in Article 8 paragraphs (2) and (2a) of the UU KUP.
The interest rate is determined monthly by the minister of finance rather than set at a single fixed rate. The calculation is based on the benchmark interest rate plus an additional percentage (uplift factor) prescribed for tax return amendments, divided by 12 and multiplied by the number of months of delay.
Interest is calculated from the expiration of the annual tax return filing deadline or the payment due date for periodic tax returns until the date the tax shortfall is paid. The penalty period is capped at 24 months.
Differences in Resolution Mechanisms
The different resolution mechanisms for tax audits and SP2DK-based oversight create different administrative burdens for taxpayers. Both aim to assess compliance and safeguard state revenue, but their resolution processes are not the same.
Resolution Through Tax Assessment Letters
A tax audit is a series of activities to objectively and professionally seek, collect, and process data and evidence in accordance with audit standards. The process may result in the issuance of a tax assessment letter (surat ketetapan pajak/SKP), in the form of an underpayment tax assessment letter (surat ketetapan pajak kurang bayar/SKPKB), a nil tax assessment letter (surat ketetapan pajak nihil/SKPN), or an overpayment tax assessment letter (surat ketetapan pajak lebih bayar/SKPLB).
Through an SKP, the DGT determines the amount of tax still payable or establishes the status of a tax overpayment. If an SKPKB is issued, taxpayers can settle their obligations based on the assessment using the appropriate billing code.
This mechanism does not, in itself, require taxpayers to amend tax returns for the tax periods or years that have been audited. The SKP serves as the basis for determining tax liabilities, while the tax returns previously submitted remain part of the filing record for those periods.
If the audit results change the amount of fiscal loss carried forward or the value-added tax (VAT) overpayment, these changes must be taken into account in subsequent tax filings in accordance with applicable regulations.
Resolution Through Tax Return Amendments Following an SP2DK
An SP2DK is an oversight instrument, not a tax assessment letter. Accordingly, an account representative cannot use an SP2DK as the basis for issuing a tax assessment. If the clarification process identifies an underpayment and the taxpayer agrees to resolve the matter by amending the tax return, the taxpayer must proceed through the mechanism prescribed under the applicable tax regulations.
Amending tax returns can increase the administrative burden on a company’s tax and accounting departments. Taxpayers must revisit transactions from previous periods, including accounting records for periods that have already been closed. If an amendment to an annual tax return affects the financial statements of a previous period, the company must assess the impact on retained earnings and determine whether the financial statements need to be restated under the applicable accounting standards.
Amending periodic VAT returns can also affect the amount of excess input VAT carried forward to subsequent periods. Changes to the carryforward balance may require adjustments to subsequent periodic returns to maintain consistency in tax reporting.
The administrative burden becomes even greater when SP2DK findings are presented only as aggregate figures. Tax returns are designed to record transactions in detail, whereas SP2DK data may show only a total discrepancy without providing the underlying transaction details. As a result, taxpayers must identify the relevant transactions, review supporting documents, and recalculate the amounts that should be reported.
| Dimension | Tax Audit Through an SKP | Oversight Through an SP2DK |
| Outcome | SKPKB, SKPN, or SKPLB, depending on the audit findings | SP2DK and documentation of the clarification results in a BAP2DK |
| Resolution mechanism | Settlement of obligations based on the tax assessment | Clarification and follow-up action based on the outcome of discussions |
| Historical reporting | Previously submitted tax returns do not automatically change | Tax return amendments are required if selected or required under applicable regulations |
| Impact on tax credits and carryforwards | Changes follow the assessment results and relevant regulations | Amendments may affect carryforward balances in subsequent tax periods |
| Administrative burden | Focuses on meeting the assessment requirements and subsequent actions | May increase if taxpayers must reconstruct transactions to support amendments |
Aggregate Findings and Exposure Codes
Data-driven oversight through Coretax relies on the integration and matching of data from various sources, including government agencies, institutions, associations, and other parties (ILAP), banks, customs documents, and third-party reports.
Systems such as compliance risk management (CRM) and web-based profile application (Aplikasi Profil Berbasis Web/Approweb) process this data to identify potential noncompliance. The analytical results may be presented using exposure codes, such as 2-1 and 2-2.
Challenges arise when an SP2DK states only the total value of a finding without providing transaction details or a transaction log. Taxpayers must independently trace the transactions responsible for the discrepancy before determining the appropriate course of action.
Exposure Code 2-1
Exposure code 2-1 relates to indications of discrepancies in reported business turnover or revenue. Coretax can compare total gross revenue reported in a corporate annual income tax return with the total tax base (dasar pengenaan pajak/DPP) reported in monthly VAT returns from January through December.
An SP2DK finding may take the form of a discrepancy between business turnover reported in the corporate annual income tax return and total supplies reported in monthly VAT returns.
Such discrepancies do not necessarily indicate unreported revenue. They may arise from differences in recognition periods, transaction characteristics, or tax treatment. Taxpayers must therefore trace the source of the discrepancy before determining whether an amendment is necessary.
If unreported revenue is identified, taxpayers must identify the relevant transactions and determine their tax treatment. Amendments to monthly VAT returns must be supported by appropriate transaction data, including the buyer’s identity where required, the type of goods or services, the transaction date, and the tax base. The issuance or amendment of tax invoices must also comply with applicable regulations.
Without transaction-level details from the DGT, companies must examine their general ledgers and supporting documents to identify the source of the discrepancy. This process can be time-consuming, particularly when transaction volumes are high and the deadline for responding to an SP2DK is limited.
Exposure Code 2-2
Exposure code 2-2 relates to indications of unfulfilled tax withholding or collection obligations. The oversight system can compare expenses recorded in the income statement, such as salaries, professional services, rent, and interest, against the tax bases reported in monthly income tax returns under Article 21, Article 23, Article 4 paragraph (2), and Article 26.
An SP2DK finding may indicate potential income tax withholding obligations that have not been fulfilled or remitted.
To address such findings, taxpayers must identify the relevant transactions, types of income, income recipients, and applicable withholding tax provisions. If an amendment is necessary, reporting through the e-Bupot or Coretax system must be supported by withholding tax slips containing the recipient’s identity and the relevant transaction information.
If an SP2DK states only total expenses without transaction-level details, taxpayers must review accounting records and supporting documents to identify the transactions underlying the finding. Without sufficient information about the transactions or parties involved, clarification and amendment become more difficult and require additional time.
Exposure Code 2-3
Exposure code 2-3 indicates discrepancies in tax data originating from third parties. The DGT system may identify tax withholding slips or input VAT invoices issued by other parties using a company’s taxpayer identification number (NPWP), even though the documents have not been recorded or claimed in the company’s tax returns.
These findings generally involve differences in input VAT or income tax credits. Such discrepancies may result from administrative errors by third parties, such as an incorrectly entered NPWP that causes tax documents to be recorded under the wrong taxpayer profile.
Resolving these findings can be challenging if the SP2DK does not include transaction-level details. Taxpayers must identify the parties that issued the documents and verify whether the transactions actually took place. If there was no transaction with the issuing party, taxpayers need to request clarification or correction from the relevant party. However, this process depends on action by a third party, which is beyond the taxpayer’s direct control.
Discrepancies between the DGT system’s analytical findings and a company’s accounting records may also result from differences in the timing of revenue recognition (timing differences) or differences in accounting classification (classification differences) under applicable financial accounting standards (SAK).
Aggregate findings in an SP2DK must therefore be investigated before taxpayers amend their tax returns. Amendments made without adequate transaction-level supporting data risk creating inconsistencies in tax reporting and accounting records. Taxpayers should not create fictitious transactions or manipulate data merely to satisfy system validation requirements.
Differences Between the Replace and Delta Approaches
The implementation of Director General of Taxes Regulation No. PER-12/PJ/2026 on October 1, 2026, changed the mechanism for filing amended tax returns through Coretax. The regulation replaced the previous provisions under PER-11/PJ/2025 and introduced the replace approach to tax return amendments.
Under the previously used delta approach, an amended tax return recorded changes to the values reported in the original return. This mechanism could produce discrepancies between the reported changes and the taxpayer’s actual tax position, including a pseudo-underpayment, in which the system indicated an underpayment even though the taxpayer’s overall tax position remained in an overpayment status.
The replace approach follows a different principle. The latest amended tax return replaces the previous return as the basis for reporting for the relevant tax period. Consequently, an amended return must contain complete and accurate transaction data and tax calculations.
Coretax then recalculates the tax liability based on the amended return and takes into account tax payments already made for the relevant tax period, including payments associated with the original return and previous amendments. The calculation also accounts for overpayments that have been refunded or carried forward in accordance with applicable regulations.
Risks of Amending Tax Returns Without Transaction Details
The replace approach requires careful consideration when taxpayers address aggregate findings in an SP2DK. At least three risks warrant attention.
1. Risk of System Validation Rejection
The replace approach requires taxpayers to reconstruct their tax return data in full. If taxpayers enter aggregate figures without transaction-level details or use invalid third-party identification information, the system may reject the filing.
This creates difficulties when an SP2DK does not provide sufficient details to identify the transactions underlying the findings. Taxpayers should therefore obtain supporting information and reconcile the relevant data before submitting an amended return.
2. Risks to Refund Applications
Amending a tax return also requires careful consideration when a taxpayer has a pending tax refund application. Before making an amendment, taxpayers should review the provisions of PER-12/PJ/2026 governing amendments to returns for tax periods associated with an ongoing tax refund process.
If an amendment affects a refund application being processed, taxpayers must determine the legal implications under the applicable regulations. This step is important to ensure that an amendment made in response to an SP2DK does not have unanticipated consequences for the tax refund process.
3. Risks to Carryforward Balances and Cash Flow
Under the replace approach, an amended tax return may change a tax overpayment balance carried forward and used in subsequent tax periods. If the previous overpayment balance decreases, taxpayers must recalculate their tax positions for the affected periods.
These changes may result in underpayments in subsequent tax periods and require sequential amendments to multiple tax returns. Before filing amendments, taxpayers should reconcile carryforward balances and calculate the potential impact on their tax liabilities and cash flow.
| Parameter | Delta Approach (PER-11/PJ/2025) | Replace Approach (PER-12/PJ/2026) |
| Reporting principle | Amended return records changes to the previous return | Amended return replaces the previous return |
| Tax calculation | Changes are calculated based on differences in reported data | Calculation is based on all data in the amended return |
| Calculation risks | May create discrepancies between the reported changes and the actual tax position | Changes may affect tax balances and carryforwards in the relevant periods |
| Impact on tax refunds | Depends on applicable regulations and the status of the refund application | Requires consideration of the rules governing amendments during the refund process |
| Resolution of aggregate SP2DK findings | Still requires identification of the underlying data supporting the changes | Requires complete reconciliation of transaction data to ensure the amended return is accurate |
Handling SP2DKs
The discrepancy between aggregate findings in SP2DKs and the detailed data required for tax return amendments calls for a measured response strategy from taxpayers. This involves data reconciliation, requests for clarification from the DGT, evidence-based responses, and risk assessments before amending tax returns through Coretax.
1. Reconciliation and Internal Data Review
Upon receiving an SP2DK, taxpayers should promptly review the data underlying the findings. Under the applicable regulations, the response deadline is 14 calendar days.
The tax department should prepare a reconciliation matrix comparing three data sources: the annual tax return, the relevant periodic tax returns, and the general ledger. This reconciliation aims to identify the source of discrepancies, including differences in transaction recognition timing, foreign exchange treatment, and accounting classification.
The results provide a basis for determining whether the findings indicate noncompliance or reflect differences in accounting records that can be explained.
2. Requesting Supporting Details for SP2DK Findings
If an SP2DK contains only aggregate figures, taxpayers should submit a written request to their account representative (AR) seeking an explanation of the basis for the findings and details of the underlying transactions.
The request may cover analytical working papers, data sources, the identities of relevant parties, transaction periods, and the methodology used to calculate discrepancies. This information is necessary for taxpayers to reconcile the DGT’s findings with their internal records and determine the appropriate follow-up action.
If the details are not yet available, taxpayers should document the issue in writing and request further clarification. A request for clarification does not automatically suspend the response deadline or halt the oversight process.
3. Preparing Evidence-Based Responses in Accordance With Applicable Rules
If internal reconciliation shows that discrepancies arise from differences in accounting classification or transaction recognition timing, taxpayers should explain these differences in their SP2DK responses, referring to the relevant tax regulations and accounting standards.
Responses should be supported by a reconciliation matrix, general ledger extracts, transaction documents, and other relevant evidence. The explanation should establish the relationship between the reported figures, the data used by the DGT, and the reasons for the discrepancies.
The objective is to provide the DGT with an adequate basis for assessing the findings and determining the appropriate follow-up action. If no noncompliance is identified, taxpayers may request that the clarification outcome be recorded in the official minutes and that the case be closed in accordance with applicable procedures.
4. Making Tax Return Amendments in a Measured Manner
If an internal review identifies an underpayment, taxpayers should calculate the impact of the amendment before submitting the amended return through Coretax.
The necessary steps include:
- Reviewing the tax payment history and carryforward balances for the relevant periods.
- Identifying the transactions underlying the adjustments and gathering supporting documents.
- Ensuring that all data entered in the amended return are accurate and verifiable.
- Simulating the impact of the amendment on carryforward balances, tax liabilities in subsequent periods, and any pending refund applications.
- Calculating the tax shortfall and administrative penalties in accordance with applicable regulations.
- Ensuring that the billing code and related payment correspond to the relevant tax type and the amended tax period or year.
Taxpayers must not enter fictitious transaction data to match the figures in an SP2DK. If transaction details are not yet available, clarification should first be pursued to the extent permitted by the applicable procedures.
Strengthening Compliance in the Coretax Era
Companies need to adjust their enterprise resource planning (ERP) systems to ensure that accounting records support tax reporting. Each revenue and expense transaction should have an appropriate tax classification, including its VAT treatment and any applicable tax withholding or collection obligations.
Tagging transactions at the initial recording stage makes it easier to reconcile general ledger entries, tax documents, and tax returns. Companies should also conduct periodic testing to ensure that data generated by their ERP systems are consistent with the information reported through Coretax.
Companies with multiple branches should implement consistent tax recording and reporting standards. Data on income tax, VAT, employee tax withholding, BPJS Ketenagakerjaan participation, and customs documentation should be reconciled in accordance with the specific requirements of each obligation.
Centralized controls help detect discrepancies at an early stage and expedite their resolution before tax returns are filed. Coordination among the tax, accounting, human resources, procurement, and customs departments is also necessary to maintain consistent information.
Taxpayers may engage licensed tax consultants, in accordance with applicable regulations, to handle complex SP2DK cases, particularly when findings involve transactions spanning multiple periods, differing interpretations of regulations, or risks to tax refund claims.
Consultants can help review the legal basis for findings, examine reconciliations, prepare responses, and assess the implications of tax return amendments. Early professional assistance can also help reduce procedural errors and ensure that decisions are based on relevant data and applicable regulations.
Conclusion
SP2DKs are an oversight instrument that gives taxpayers an opportunity to explain data discrepancies and address their tax obligations in accordance with applicable regulations. However, aggregate findings without transaction-level details can complicate clarification and tax return amendments, particularly when the required information is not available in a readily usable format.
The differences between the resolution mechanisms for SP2DKs and tax audits also warrant attention. A tax audit may result in a tax assessment letter establishing the taxpayer’s liabilities, whereas follow-up action on an SP2DK depends on the clarification outcome and the relevant tax procedures. Taxpayers should therefore understand the administrative and financial implications before deciding to amend their returns.
The implementation of the replace approach in Coretax further underscores the importance of conducting a comprehensive review before making amendments. Taxpayers need to assess the impact on carryforward balances, tax liabilities in subsequent periods, and pending refund applications.
To mitigate risks, companies should conduct regular data reconciliations, request clarification of findings that remain unclear, prepare evidence-based responses, and ensure that every amendment is supported by valid transaction data. In the long term, aligning accounting systems, strengthening cross-departmental reporting controls, and obtaining professional assistance when needed can reinforce compliance and reduce administrative challenges associated with data-driven tax oversight.
Legal References
- Law of the Republic of Indonesia Number 6 of 1983 concerning General Provisions and Tax Procedures, as amended several times, most recently by Law of the Republic of Indonesia Number 6 of 2023 concerning the Enactment of Government Regulation in Lieu of Law Number 2 of 2022 concerning Job Creation into Law.
- Law of the Republic of Indonesia Number 7 of 2021 concerning the Harmonization of Tax Regulations.
- Law of the Republic of Indonesia Number 6 of 2023 concerning the Enactment of Government Regulation in Lieu of Law Number 2 of 2022 concerning Job Creation into Law.
- Government Regulation in Lieu of Law of the Republic of Indonesia Number 2 of 2022 concerning Job Creation.
- Minister of Finance Regulation Number 111 of 2025 concerning Taxpayer Compliance Oversight.
- Circular Letter of the Director General of Taxes Number SE-05/PJ/2022 concerning Taxpayer Compliance Oversight.
- Circular Letter of the Director General of Taxes Number SE-8/PJ/2026 concerning Technical Guidelines for Taxpayer Compliance Oversight.
- Director General of Taxes Regulation Number PER-11/PJ/2025 concerning Tax Reporting Requirements for Income Tax, Value-Added Tax, Luxury Goods Sales Tax, and Stamp Duty under the Core Tax Administration System.
- Director General of Taxes Regulation Number PER-12/PJ/2026 concerning Amendments to Director General of Taxes Regulation Number PER-11/PJ/2025 concerning Tax Reporting Requirements for Income Tax, Value-Added Tax, Luxury Goods Sales Tax, and Stamp Duty under the Core Tax Administration System.
Also Read:
SP2DK Findings Without Transaction Details: What Taxpayers Need to Know
Understanding SP2DK: Purpose, Process, and How to Respond
Larangan Merekam dalam Proses SP2DK dan Kesetaraan Prosedural
Editor: Thomas Rizal