
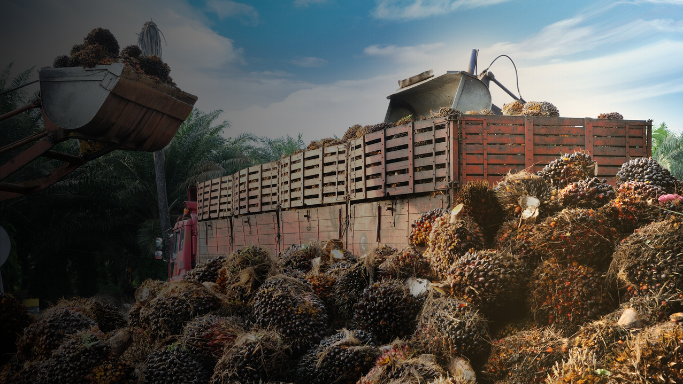
Indonesia’s plan to centralize exports of natural resources moves forward with the establishment of PT Danantara Sumberdaya Indonesia (DSI). This state-backed entity will serve as the sole export operator for several strategic commodities, including coal, crude palm oil (CPO), and ferroalloys.
The transition was scheduled to begin on June 1, 2026, before the system becomes fully operational on January 1, 2027.
Under the new framework, producers will no longer sell directly to overseas buyers. Instead, commodities will be sold to DSI, which will act as the official exporter to international markets.
The government argues that the model will advance Indonesia’s negotiating position in global trade while improving transparency in export transactions.
One of the long-standing concerns in Indonesia’s commodity sector has been the risk of under-invoicing and transfer pricing. When export prices are reported below prevailing market levels, the state can lose both tax revenue and foreign exchange earnings. By consolidating export transactions under a single entity, policymakers hope to record commodity prices more accurately and benchmark them against international markets.
For companies operating in mining, plantation, and mineral processing sectors, however, the policy represents a significant shift. Export marketing functions previously handled internally may increasingly shift to DSI, leaving companies to focus on production, processing, and quality control.
If Indonesia succeeds in improving price transparency across commodity exports, attention may increasingly shift to how extraordinary profits are taxed. Periods of elevated prices for coal, crude oil, and palm oil have generated significant windfall gains for producers, prompting consideration of whether a portion of those profits should be returned to the public through the tax system.
What Is a Windfall Tax?

A windfall tax is an additional levy imposed on profits that arise from extraordinary market conditions rather than from a company’s own operational improvements.
These gains are typically driven by external events such as commodity price spikes, energy crises, geopolitical conflicts, or global political shifts.
The rationale behind a windfall tax is rooted in the concept of fiscal fairness. If unforeseen events generate substantial profits for a small group of companies while imposing economic costs on the wider public, governments may seek to redistribute part of those gains through taxation. Revenue collected from such taxes is often used to fund subsidies, social assistance programs, or measures designed to offset rising living costs.
A Temporary Tax
Unlike corporate income tax, which applies on an ongoing basis, windfall taxes are generally temporary. They are introduced during periods of exceptional profitability and are often targeted at specific industries.
For this reason, economists frequently describe this tax as a one-off tax.
Windfall Tax Across Countries

United Kingdom
The modern debate over windfall taxes gained momentum during the global energy crisis that followed Russia’s invasion of Ukraine in 2022. As oil and gas prices surged, energy producers reported record earnings while households faced soaring electricity and heating bills.
In response, the UK introduced Energy Profits Levy (EPL), an additional tax on North Sea oil and gas producers. The government argued that part of these extraordinary profits should be used to support households struggling with higher energy costs.
The policy was later expanded to include certain electricity generators that also benefited from elevated energy prices, indicating that windfall taxes can extend beyond traditional extractive industries.
Italy
Italy adopted a similar approach in 2022, introducing an additional levy on energy companies to help finance relief measures for households and businesses.
While the measure generated substantial revenue, it also reflects the legal challenges that can accompany windfall taxes. Several companies challenged the policy in court, and the country’s constitutional court ultimately scrutinized parts of the framework.
The experience shows that windfall taxes require clear legal foundations and carefully designed tax bases to withstand challenge.
European Union
The European Union also embraced the concept during the energy crisis through a temporary solidarity contribution imposed on fossil fuel companies. Rather than adopting a single EU-wide tax, member states were given flexibility to design their own measures within a common policy framework. The initiative demonstrated how windfall taxes can be used as a coordinated fiscal response during periods of economic stress.
Australia
Australia has long experimented with various forms of resource taxation intended to capture a greater share of profits generated from mining and energy projects. While the structure differs from European windfall taxes, the underlying objective is similar, which is to contribute extraordinary gains from natural resources to public finances broadly.
United States
The US introduced the Crude Oil Windfall Profit Tax Act of 1980 after a sharp increase in global oil prices. The tax was designed to capture a portion of the additional profits oil producers earned following the deregulation of domestic oil prices. Although the policy remains a prominent reference point in tax debates, its effectiveness continues to be discussed decades after its repeal.
Fairness vs. Investment Debate
Supporters argue that windfall taxes are a matter of economic fairness. When households face inflation, rising energy costs, or broader economic hardship, governments may have a legitimate reason to tax extraordinary corporate profits and redistribute part of the gains to society.
Because such taxes are temporary, proponents also argue that they are less distortionary than permanent tax increases.
Critics, however, warn that windfall taxes can create uncertainty for investors. If companies believe that periods of strong profitability will trigger additional taxation, they may become more cautious about future investment decisions.
Regime uncertainty may affect large-scale projects in mining, energy, and natural resources that often require billions of dollars in long-term investment. Another challenge lies in defining what constitutes a windfall. Commodity markets are inherently cyclical. Periods of exceptional profits are often followed by sharp downturns, making it difficult to determine when profits are extraordinary rather than simply part of the normal business cycle.
Could Indonesia Adopt a Windfall Tax?
Indonesia has periodically revisited the idea of a windfall tax whenever prices of coal, CPO, nickel, or other major export commodities surge.
Although the country does not currently operate a dedicated windfall tax regime like those seen in parts of Europe, the discussion regularly resurfaces during commodity booms. When global prices generate unexpected profits, the state should have a mechanism to capture a greater share of those gains for public benefit.
The experiences of the UK, Italy, EU, Australia, and the US suggest that the success of any windfall tax depends not only on the rate imposed but also on the clarity of its legal basis, the precision of its design, and the confidence it inspires among investors.
